CFO COMMENTARY AND FINANCIAL REVIEW THIRD QUARTER 2026 September 30, 2026 Exhibit 99.2
This presentation does not constitute an offer or invitation for the sale or purchase of securities and has been prepared solely for informational purposes. This presentation contains forward-looking statements within the meaning of the federal securities laws regarding Columbia Sportswear Company’s business opportunities and anticipated results of operations. Forward-looking statements generally relate to future events or our future financial or operating performance. In some cases, you can identify forward- looking statements because they contain words such as “may,” “might,” “will,” “would,” “should,” “expect,” “plan,” “anticipate,” “could,” “intend,” “target,” “project,” “contemplate,” “believe,” “estimate,” “predict,” “likely,” “goal,” “potential” or “continue” or the negative of these words or other similar terms or expressions that concern our expectations, strategy, plans or intentions. Unless the context indicates otherwise, the terms "we," "us," "our," "the Company," and "Columbia" refer to Columbia Sportswear Company, together with its wholly owned subsidiaries and entities in which it maintains a controlling financial interest. The Company's expectations, beliefs and projections are expressed in good faith and are believed to have a reasonable basis; however, each forward-looking statement involves a number of risks and uncertainties, including those set forth in this document, those described in the Company's Annual Report on Form 10-K and Quarterly Reports on Form 10-Q under the heading "Risk Factors," and those that have been or may be described in other reports filed by the Company, including reports on Form 8-K. Potential risks and uncertainties that may affect our future revenues, costs, earnings and performance and could cause the actual results of operations or financial condition of the Company to differ materially from the anticipated results expressed or implied by forward-looking statements in this document include: loss of key customer accounts; our ability to execute the ACCELERATE Growth Strategy; our ability to effectively execute our business strategies, including initiatives to upgrade our business processes and information technology (“IT”) systems and investments in our DTC businesses; our ability to maintain the strength and security of our IT systems; the effects of unseasonable weather, including global climate change; the seasonality of our business and timing of orders; trends affecting consumer spending, including changes in the level of consumer spending, and retail traffic patterns; unfavorable economic conditions generally; the financial health of our customers and retailer consolidation; higher than expected rates of order cancellations; changes affecting consumer demand and preferences and fashion trends; changes in international, federal or state tax, labor and other laws and regulations that affect our business, including changes in corporate tax rates, tariffs, international trade policy and geopolitical tensions, or increasing wage rates; our ability to attract and retain key personnel; risks inherent in doing business in foreign markets, including fluctuations in currency exchange rates, global credit market conditions, changes in global regulation and economic and political conditions and disease outbreaks; volatility in global production and transportation costs and capacity and timing; our ability to effectively manage our inventory and our wholesale customers’ ability to manage their inventories; our dependence on third- party manufacturers and suppliers and our ability to source at competitive prices from them or at all and our ability to import product; the effectiveness of our sales and marketing efforts; business disruptions and acts of terrorism, cyber-attacks or military activities around the globe; intense competition in the industry; our ability to establish and protect our intellectual property; and our ability to develop innovative products. The Company cautions that forward-looking statements are inherently less reliable than historical information. New risks and uncertainties emerge from time to time and it is not possible for the Company to predict all risks and uncertainties that could have an impact on the forward-looking statements contained in this presentation. Nothing in this presentation should be regarded as a representation by any person that the forward-looking statements set forth herein will be achieved or that any of the contemplated results of such forward-looking statements will be achieved. You should not place undue reliance on forward-looking statements, which speak only as of the date they are made. We do not undertake any duty to update any of the forward-looking statements after the date of this document to conform the forward-looking statements to actual results or to changes in our expectations. FORWARD-LOOKING STATEMENTS
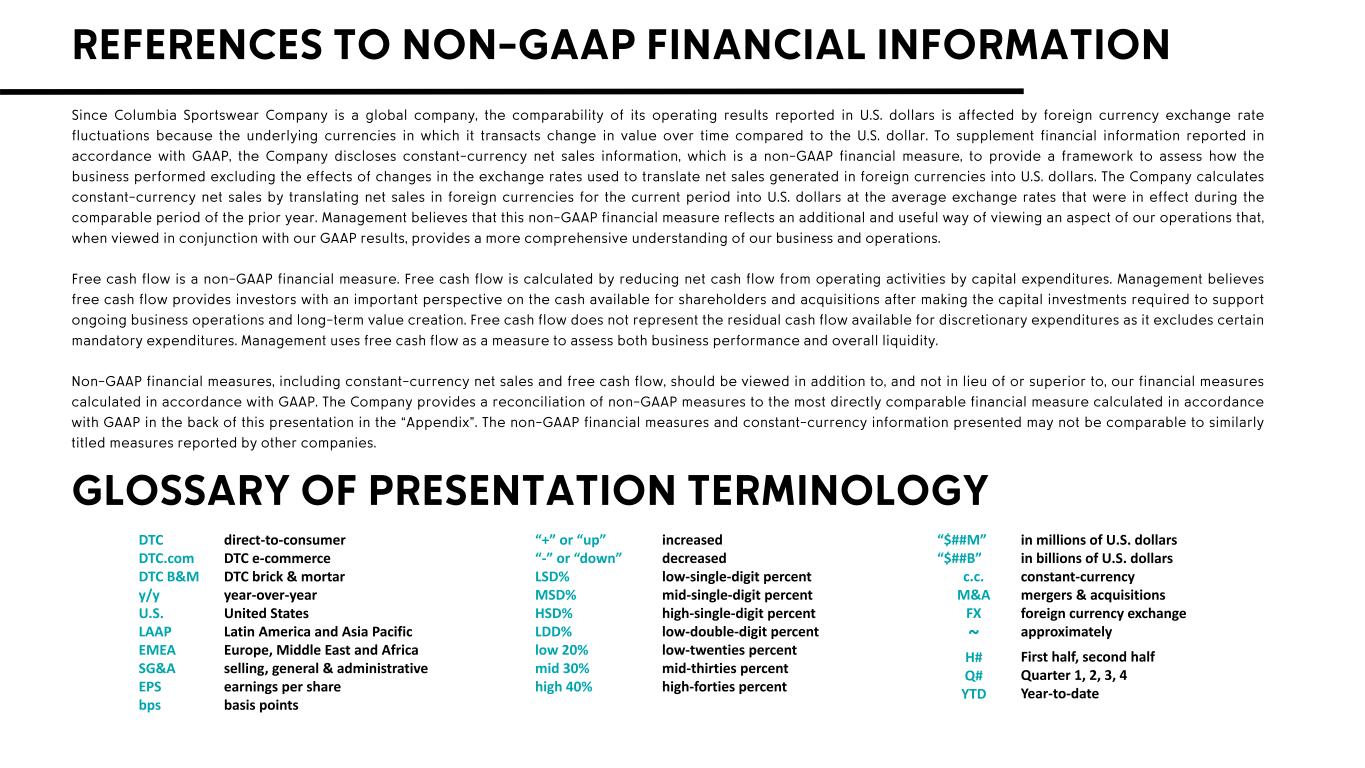
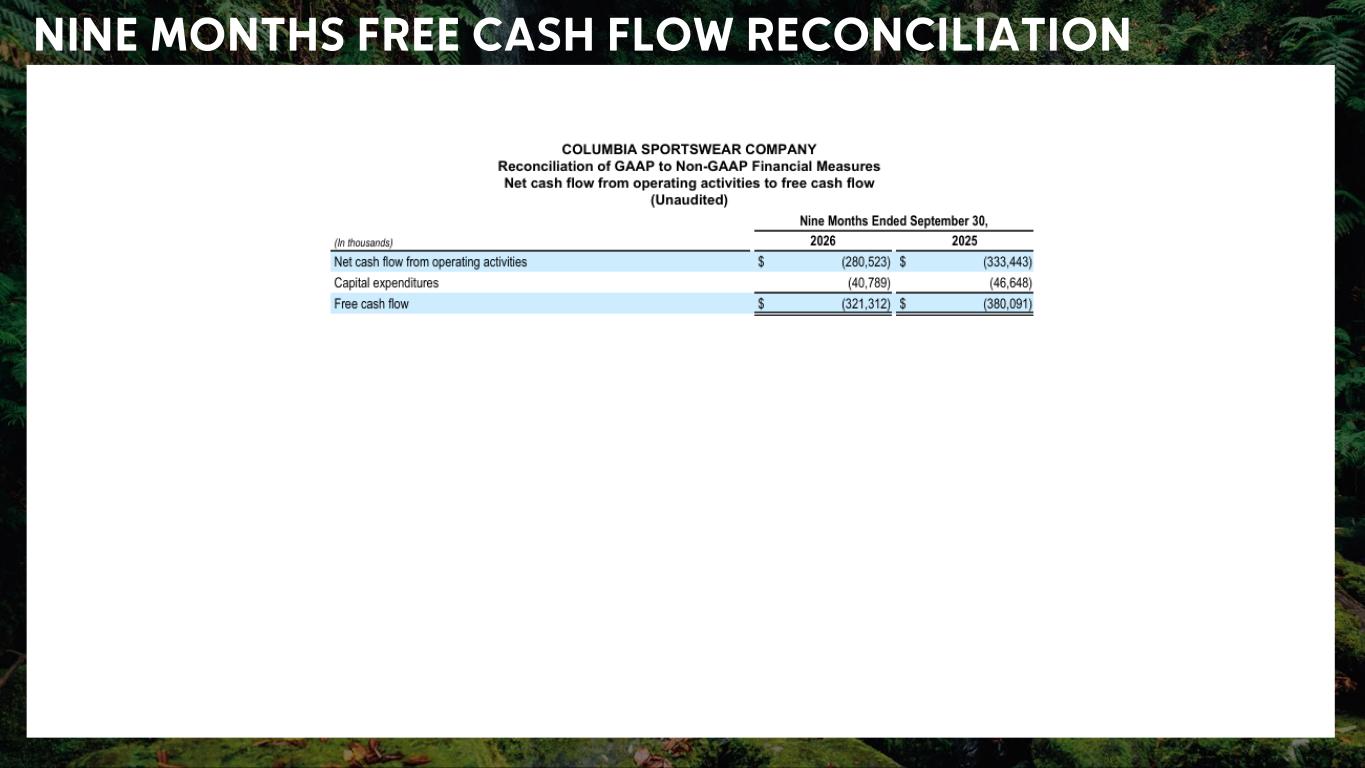
Since Columbia Sportswear Company is a global company, the comparability of its operating results reported in U.S. dollars is affected by foreign currency exchange rate fluctuations because the underlying currencies in which it transacts change in value over time compared to the U.S. dollar. To supplement financial information reported in accordance with GAAP, the Company discloses constant-currency net sales information, which is a non-GAAP financial measure, to provide a framework to assess how the business performed excluding the effects of changes in the exchange rates used to translate net sales generated in foreign currencies into U.S. dollars. The Company calculates constant-currency net sales by translating net sales in foreign currencies for the current period into U.S. dollars at the average exchange rates that were in effect during the comparable period of the prior year. Management believes that this non-GAAP financial measure reflects an additional and useful way of viewing an aspect of our operations that, when viewed in conjunction with our GAAP results, provides a more comprehensive understanding of our business and operations. Free cash flow is a non-GAAP financial measure. Free cash flow is calculated by reducing net cash flow from operating activities by capital expenditures. Management believes free cash flow provides investors with an important perspective on the cash available for shareholders and acquisitions after making the capital investments required to support ongoing business operations and long-term value creation. Free cash flow does not represent the residual cash flow available for discretionary expenditures as it excludes certain mandatory expenditures. Management uses free cash flow as a measure to assess both business performance and overall liquidity. Non-GAAP financial measures, including constant-currency net sales and free cash flow, should be viewed in addition to, and not in lieu of or superior to, our financial measures calculated in accordance with GAAP. The Company provides a reconciliation of non-GAAP measures to the most directly comparable financial measure calculated in accordance with GAAP in the back of this presentation in the “Appendix”. The non-GAAP financial measures and constant-currency information presented may not be comparable to similarly titled measures reported by other companies. REFERENCES TO NON-GAAP FINANCIAL INFORMATION GLOSSARY OF PRESENTATION TERMINOLOGY DTC DTC.com DTC B&M y/y U.S. LAAP EMEA SG&A EPS bps direct-to-consumer DTC e-commerce DTC brick & mortar year-over-year United States Latin America and Asia Pacific Europe, Middle East and Africa selling, general & administrative earnings per share basis points “+” or “up” “-” or “down” LSD% MSD% HSD% LDD% low 20% mid 30% high 40% increased decreased low-single-digit percent mid-single-digit percent high-single-digit percent low-double-digit percent low-twenties percent mid-thirties percent high-forties percent “$##M” “$##B” c.c. M&A FX ~ H# Q# YTD in millions of U.S. dollars in billions of U.S. dollars constant-currency mergers & acquisitions foreign currency exchange approximately First half, second half Quarter 1, 2, 3, 4 Year-to-date
ACCELERATE PROFITABLE GROWTH CREATE ICONIC PRODUCTS Differentiated, Functional, Innovative DRIVE BRAND ENGAGEMENT Increased, Focused Demand Creation Investments ENHANCE CONSUMER EXPERIENCES Invest in Capabilities to Delight and Retain Consumers AMPLIFY MARKETPLACE EXCELLENCE Digitally-Led, Omni-Channel, Global EMPOWER TALENT THAT IS DRIVEN BY OUR CORE VALUES Through a Diverse and Inclusive Workforce W E C O N N E C T A C T I V E P E O P L E W I T H T H E I R P A S S I O N S
CAPITAL ALLOCATION PRIORITIES DEPENDENT UPON OUR FINANCIAL POSITION, MARKET CONDITIONS AND OUR STRATEGIC PRIORITIES, OUR CAPITAL ALLOCATION APPROACH INCLUDES: INVEST IN ORGANIC GROWTH OPPORTUNITIES RETURN AT LEAST 40% OF FREE CASH FLOW TO SHAREHOLDERS OPPORTUNISTIC M&A TO DRIVE LONG-TERM PROFITABLE GROWTH THROUGH DIVIDENDS AND SHARE REPURCHASES OUR GOAL IS TO MAINTAIN OUR STRONG BALANCE SHEET AND DISCIPLINED APPROACH TO CAPITAL ALLOCATION.
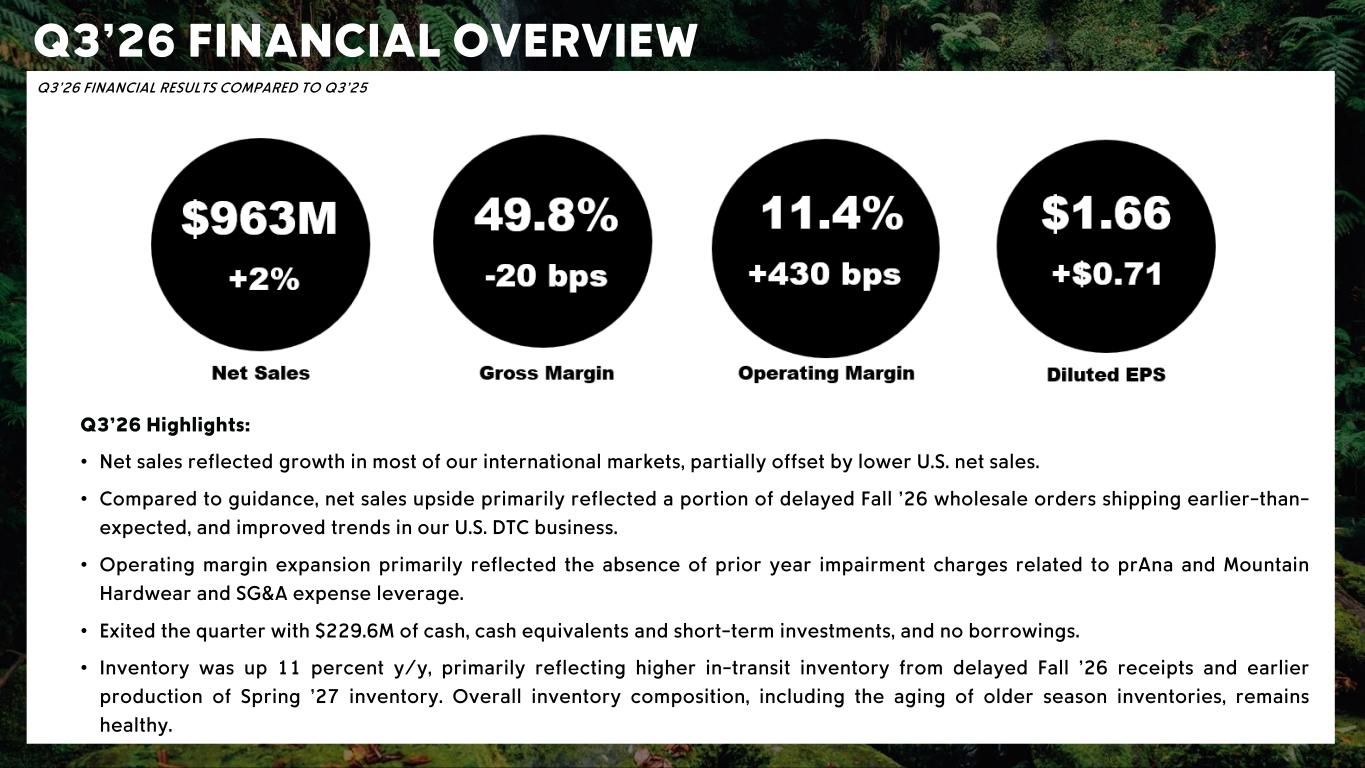
Q3’26 FINANCIAL OVERVIEW Q3’26 FINANCIAL RESULTS COMPARED TO Q3’25 Q3’26 Highlights: • Net sales reflected growth in most of our international markets, partially offset by lower U.S. net sales. • Compared to guidance, net sales upside primarily reflected a portion of delayed Fall ’26 wholesale orders shipping earlier-than- expected, and improved trends in our U.S. DTC business. • Operating margin expansion primarily reflected the absence of prior year impairment charges related to prAna and Mountain Hardwear and SG&A expense leverage. • Exited the quarter with $229.6M of cash, cash equivalents and short-term investments, and no borrowings. • Inventory was up 11 percent y/y, primarily reflecting higher in-transit inventory from delayed Fall ’26 receipts and earlier production of Spring ’27 inventory. Overall inventory composition, including the aging of older season inventories, remains healthy.
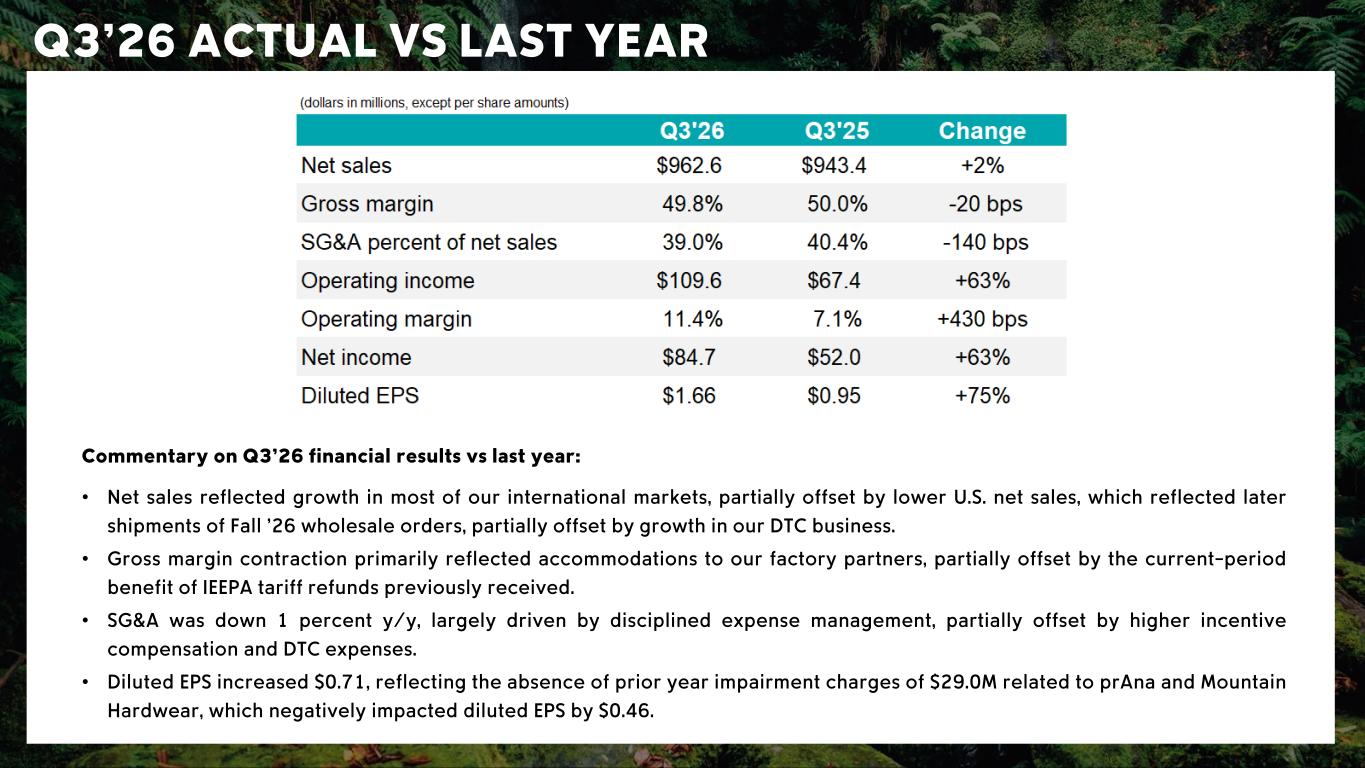
Q3’26 ACTUAL VS LAST YEAR Commentary on Q3’26 financial results vs last year: • Net sales reflected growth in most of our international markets, partially offset by lower U.S. net sales, which reflected later shipments of Fall ’26 wholesale orders, partially offset by growth in our DTC business. • Gross margin contraction primarily reflected accommodations to our factory partners, partially offset by the current-period benefit of IEEPA tariff refunds previously received. • SG&A was down 1 percent y/y, largely driven by disciplined expense management, partially offset by higher incentive compensation and DTC expenses. • Diluted EPS increased $0.71, reflecting the absence of prior year impairment charges of $29.0M related to prAna and Mountain Hardwear, which negatively impacted diluted EPS by $0.46.
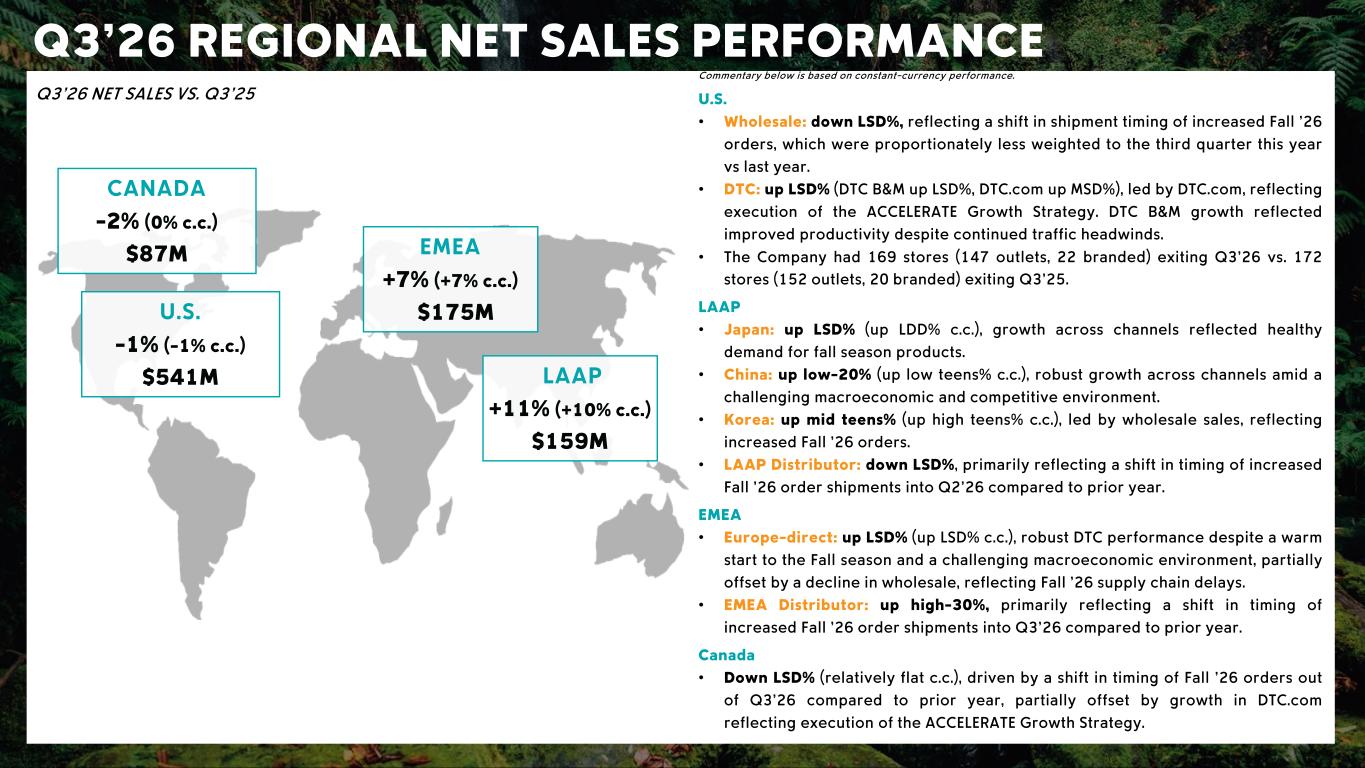
Q3’26 REGIONAL NET SALES PERFORMANCE Commentary below is based on constant-currency performance. U.S. • Wholesale: down LSD%, reflecting a shift in shipment timing of increased Fall ’26 orders, which were proportionately less weighted to the third quarter this year vs last year. • DTC: up LSD% (DTC B&M up LSD%, DTC.com up MSD%), led by DTC.com, reflecting execution of the ACCELERATE Growth Strategy. DTC B&M growth reflected improved productivity despite continued traffic headwinds. • The Company had 169 stores (147 outlets, 22 branded) exiting Q3’26 vs. 172 stores (152 outlets, 20 branded) exiting Q3’25. LAAP • Japan: up LSD% (up LDD% c.c.), growth across channels reflected healthy demand for fall season products. • China: up low-20% (up low teens% c.c.), robust growth across channels amid a challenging macroeconomic and competitive environment. • Korea: up mid teens% (up high teens% c.c.), led by wholesale sales, reflecting increased Fall ’26 orders. • LAAP Distributor: down LSD%, primarily reflecting a shift in timing of increased Fall ’26 order shipments into Q2’26 compared to prior year. EMEA • Europe-direct: up LSD% (up LSD% c.c.), robust DTC performance despite a warm start to the Fall season and a challenging macroeconomic environment, partially offset by a decline in wholesale, reflecting Fall ’26 supply chain delays. • EMEA Distributor: up high-30%, primarily reflecting a shift in timing of increased Fall ’26 order shipments into Q3’26 compared to prior year. Canada • Down LSD% (relatively flat c.c.), driven by a shift in timing of Fall ’26 orders out of Q3’26 compared to prior year, partially offset by growth in DTC.com reflecting execution of the ACCELERATE Growth Strategy. Q3’26 NET SALES VS. Q3’25 CANADA -2% (0% c.c.) $87M U.S. -1% (-1% c.c.) $541M EMEA +7% (+7% c.c.) $175M LAAP +11% (+10% c.c.) $159M
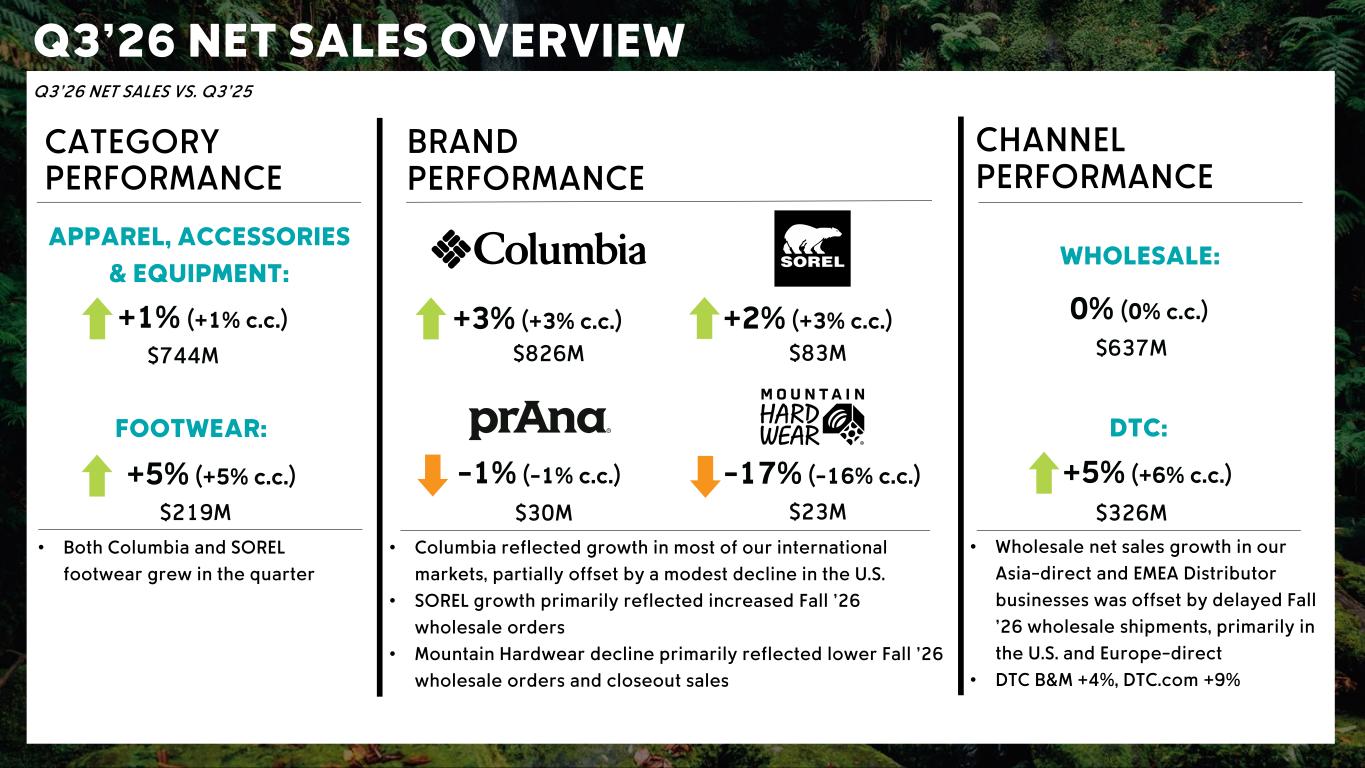
Q3’26 NET SALES OVERVIEW Q3’26 NET SALES VS. Q3’25 CATEGORY PERFORMANCE CHANNEL PERFORMANCE WHOLESALE: DTC: +5% (+6% c.c.) $637M $326M 0% (0% c.c.) • Both Columbia and SOREL footwear grew in the quarter • Columbia reflected growth in most of our international markets, partially offset by a modest decline in the U.S. • SOREL growth primarily reflected increased Fall ’26 wholesale orders • Mountain Hardwear decline primarily reflected lower Fall ’26 wholesale orders and closeout sales • Wholesale net sales growth in our Asia-direct and EMEA Distributor businesses was offset by delayed Fall ’26 wholesale shipments, primarily in the U.S. and Europe-direct • DTC B&M +4%, DTC.com +9% APPAREL, ACCESSORIES & EQUIPMENT: $744M +1% (+1% c.c.) FOOTWEAR: +5% (+5% c.c.) $219M BRAND PERFORMANCE +3% (+3% c.c.) $826M +2% (+3% c.c.) $83M -1% (-1% c.c.) $30M -17% (-16% c.c.) $23M
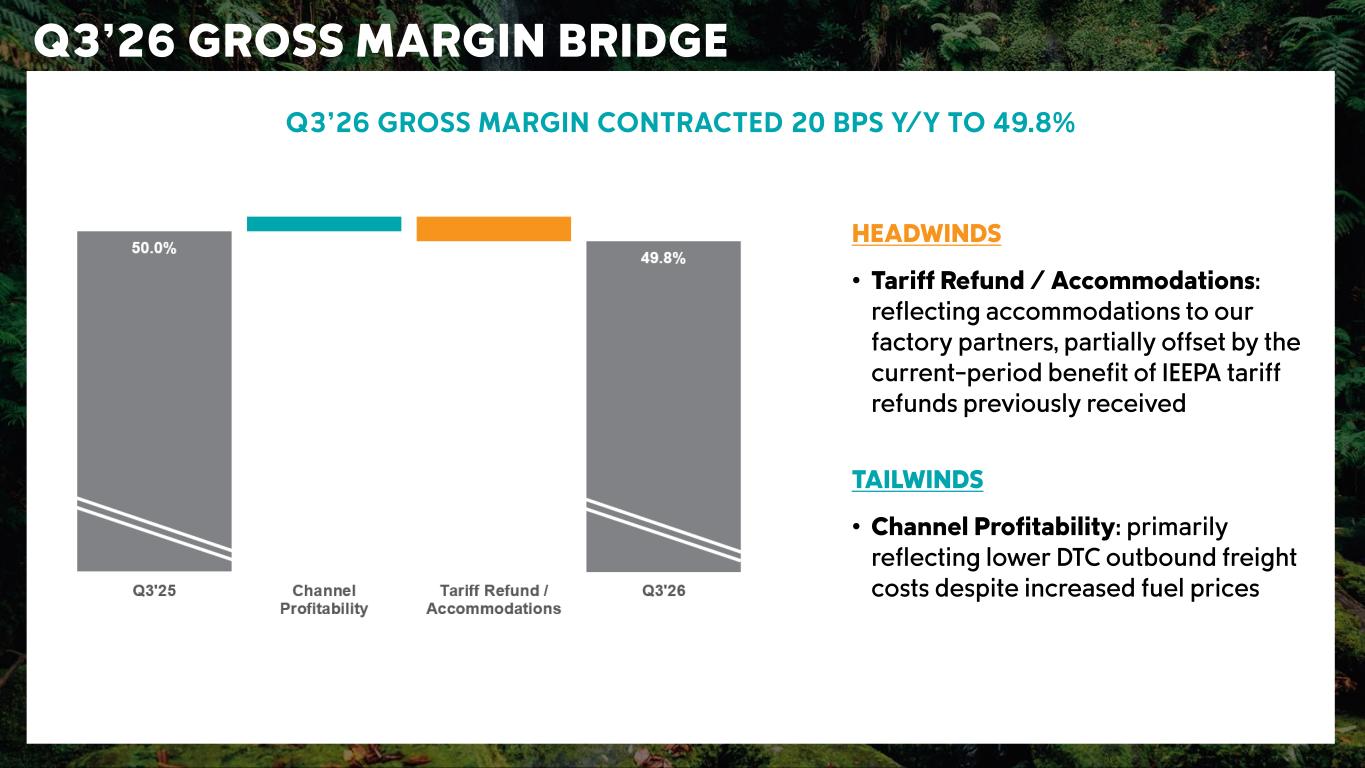
Q3’26 GROSS MARGIN BRIDGE HEADWINDS • Tariff Refund / Accommodations: reflecting accommodations to our factory partners, partially offset by the current-period benefit of IEEPA tariff refunds previously received TAILWINDS • Channel Profitability: primarily reflecting lower DTC outbound freight costs despite increased fuel prices Q3’26 GROSS MARGIN CONTRACTED 20 BPS Y/Y TO 49.8%
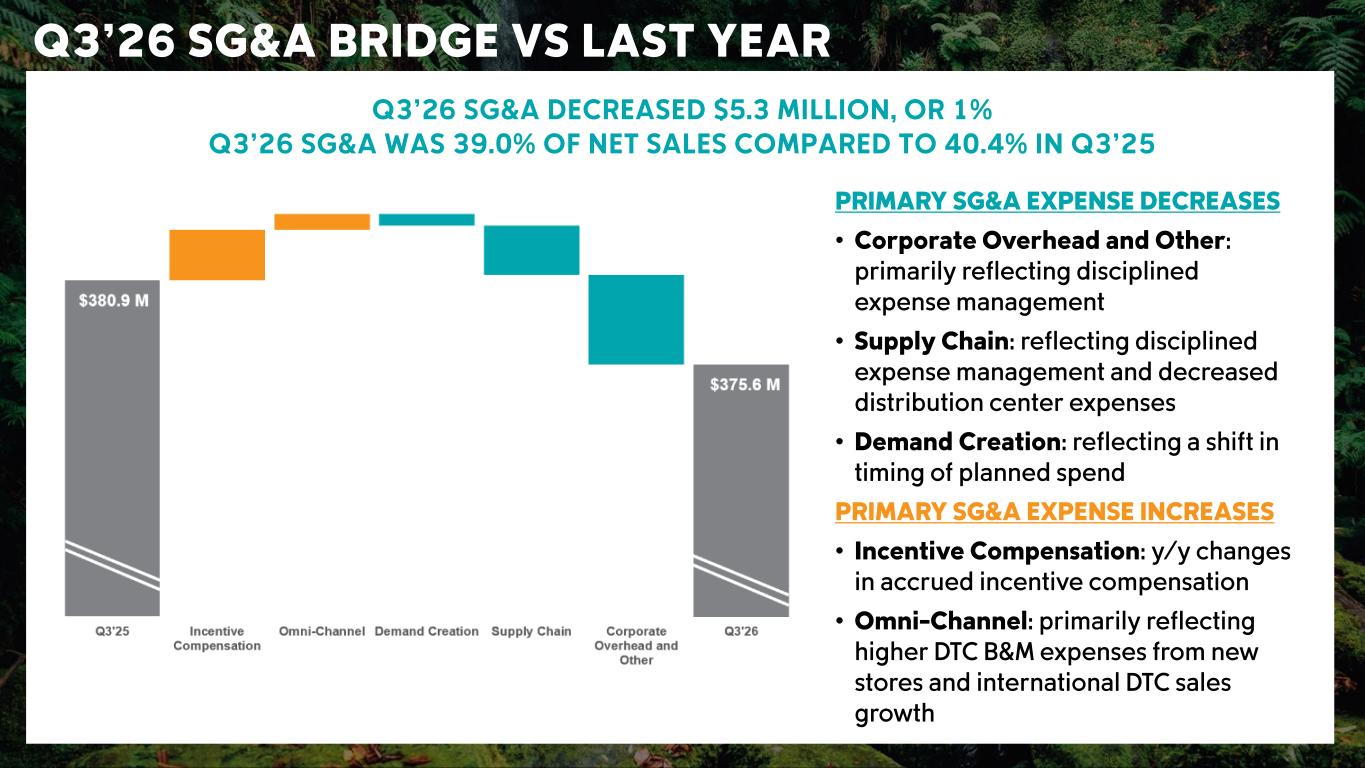
Q3’26 SG&A BRIDGE VS LAST YEAR * Excludes Retail; ** Excludes Advertising Q3’26 SG&A DECREASED $5.3 MILLION, OR 1% Q3’26 SG&A WAS 39.0% OF NET SALES COMPARED TO 40.4% IN Q3’25 PRIMARY SG&A EXPENSE DECREASES • Corporate Overhead and Other: primarily reflecting disciplined expense management • Supply Chain: reflecting disciplined expense management and decreased distribution center expenses • Demand Creation: reflecting a shift in timing of planned spend PRIMARY SG&A EXPENSE INCREASES • Incentive Compensation: y/y changes in accrued incentive compensation • Omni-Channel: primarily reflecting higher DTC B&M expenses from new stores and international DTC sales growth
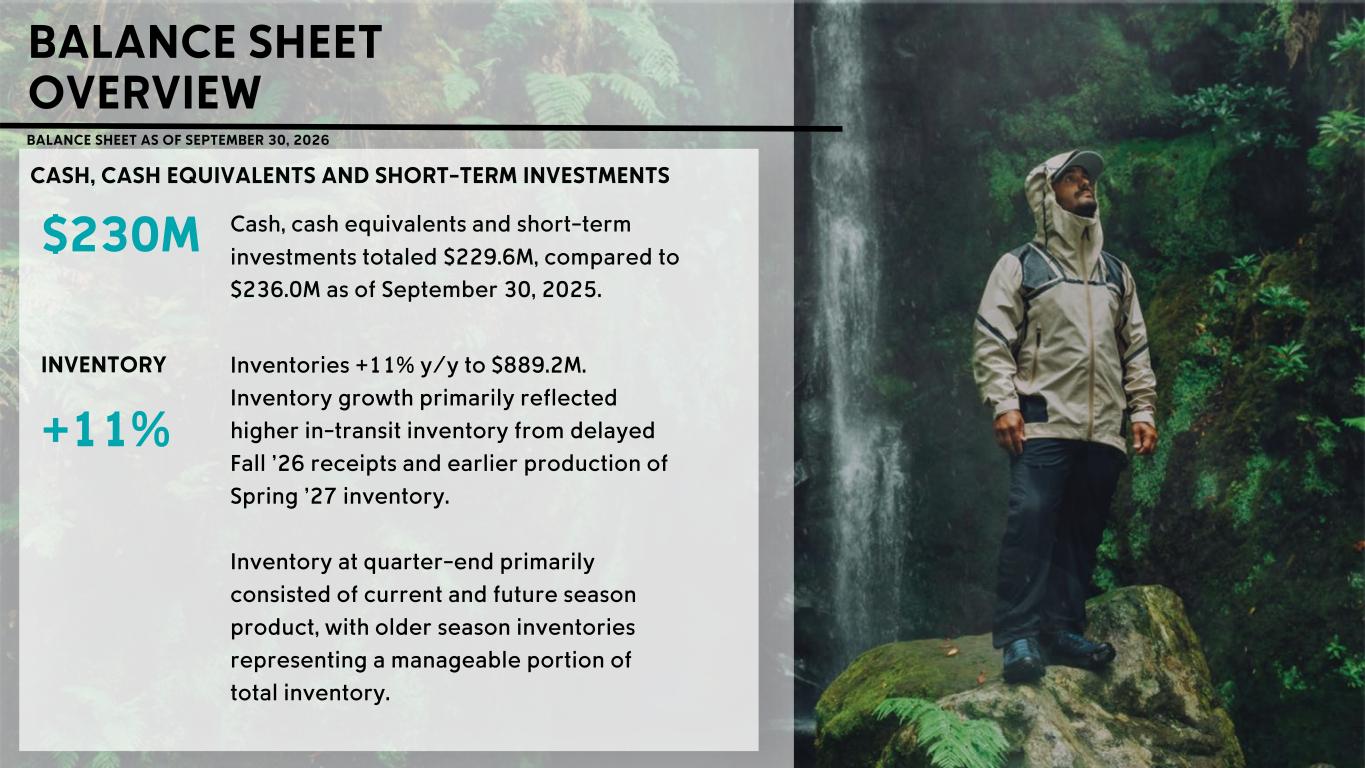
BALANCE SHEET OVERVIEW Cash, cash equivalents and short-term investments totaled $229.6M, compared to $236.0M as of September 30, 2025. $230M +11% BALANCE SHEET AS OF SEPTEMBER 30, 2026 INVENTORY CASH, CASH EQUIVALENTS AND SHORT-TERM INVESTMENTS Inventories +11% y/y to $889.2M. Inventory growth primarily reflected higher in-transit inventory from delayed Fall ’26 receipts and earlier production of Spring ’27 inventory. Inventory at quarter-end primarily consisted of current and future season product, with older season inventories representing a manageable portion of total inventory.
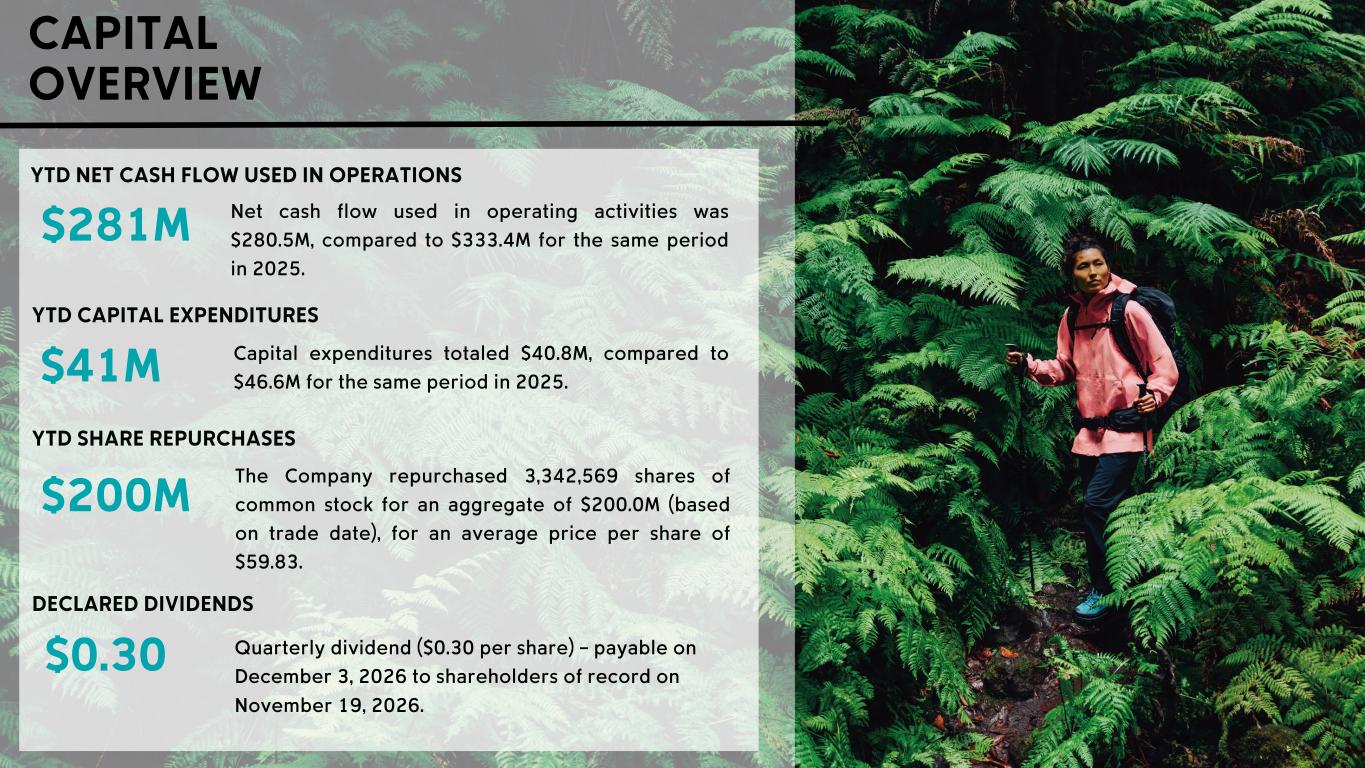
CAPITAL OVERVIEW $281M Net cash flow used in operating activities was $280.5M, compared to $333.4M for the same period in 2025. Capital expenditures totaled $40.8M, compared to $46.6M for the same period in 2025. $200M The Company repurchased 3,342,569 shares of common stock for an aggregate of $200.0M (based on trade date), for an average price per share of $59.83. YTD SHARE REPURCHASES YTD CAPITAL EXPENDITURES YTD NET CASH FLOW USED IN OPERATIONS $0.30 Quarterly dividend ($0.30 per share) – payable on December 3, 2026 to shareholders of record on November 19, 2026. DECLARED DIVIDENDS $41M
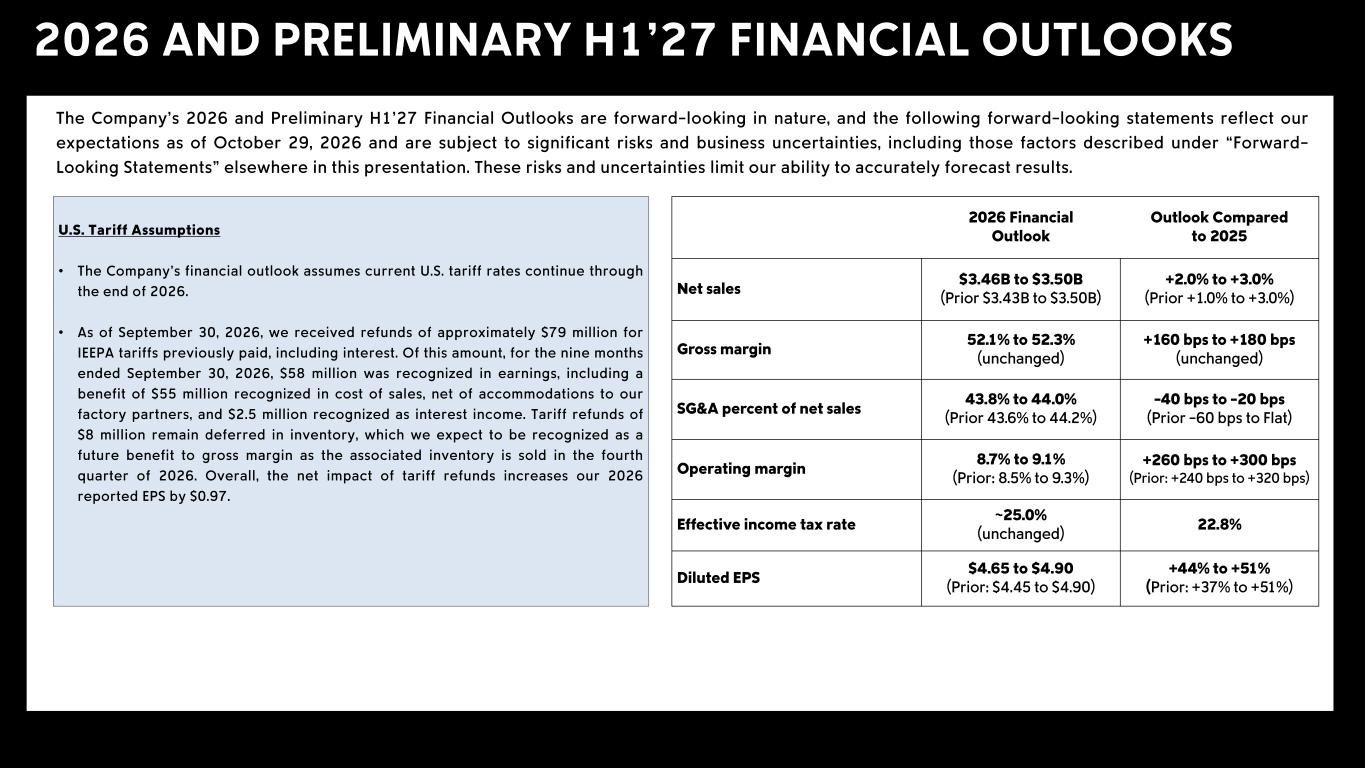
2026 AND PRELIMINARY H1’27 FINANCIAL OUTLOOKS The Company’s 2026 and Preliminary H1’27 Financial Outlooks are forward-looking in nature, and the following forward-looking statements reflect our expectations as of October 29, 2026 and are subject to significant risks and business uncertainties, including those factors described under “Forward- Looking Statements” elsewhere in this presentation. These risks and uncertainties limit our ability to accurately forecast results. 2026 Financial Outlook Outlook Compared to 2025 Net sales $3.46B to $3.50B (Prior $3.43B to $3.50B) +2.0% to +3.0% (Prior +1.0% to +3.0%) Gross margin 52.1% to 52.3% (unchanged) +160 bps to +180 bps (unchanged) SG&A percent of net sales 43.8% to 44.0% (Prior 43.6% to 44.2%) -40 bps to -20 bps (Prior -60 bps to Flat) Operating margin 8.7% to 9.1% (Prior: 8.5% to 9.3%) +260 bps to +300 bps (Prior: +240 bps to +320 bps) Effective income tax rate ~25.0% (unchanged) 22.8% Diluted EPS $4.65 to $4.90 (Prior: $4.45 to $4.90) +44% to +51% (Prior: +37% to +51%) U.S. Tariff Assumptions • The Company’s financial outlook assumes current U.S. tariff rates continue through the end of 2026. • As of September 30, 2026, we received refunds of approximately $79 million for IEEPA tariffs previously paid, including interest. Of this amount, for the nine months ended September 30, 2026, $58 million was recognized in earnings, including a benefit of $55 million recognized in cost of sales, net of accommodations to our factory partners, and $2.5 million recognized as interest income. Tariff refunds of $8 million remain deferred in inventory, which we expect to be recognized as a future benefit to gross margin as the associated inventory is sold in the fourth quarter of 2026. Overall, the net impact of tariff refunds increases our 2026 reported EPS by $0.97.
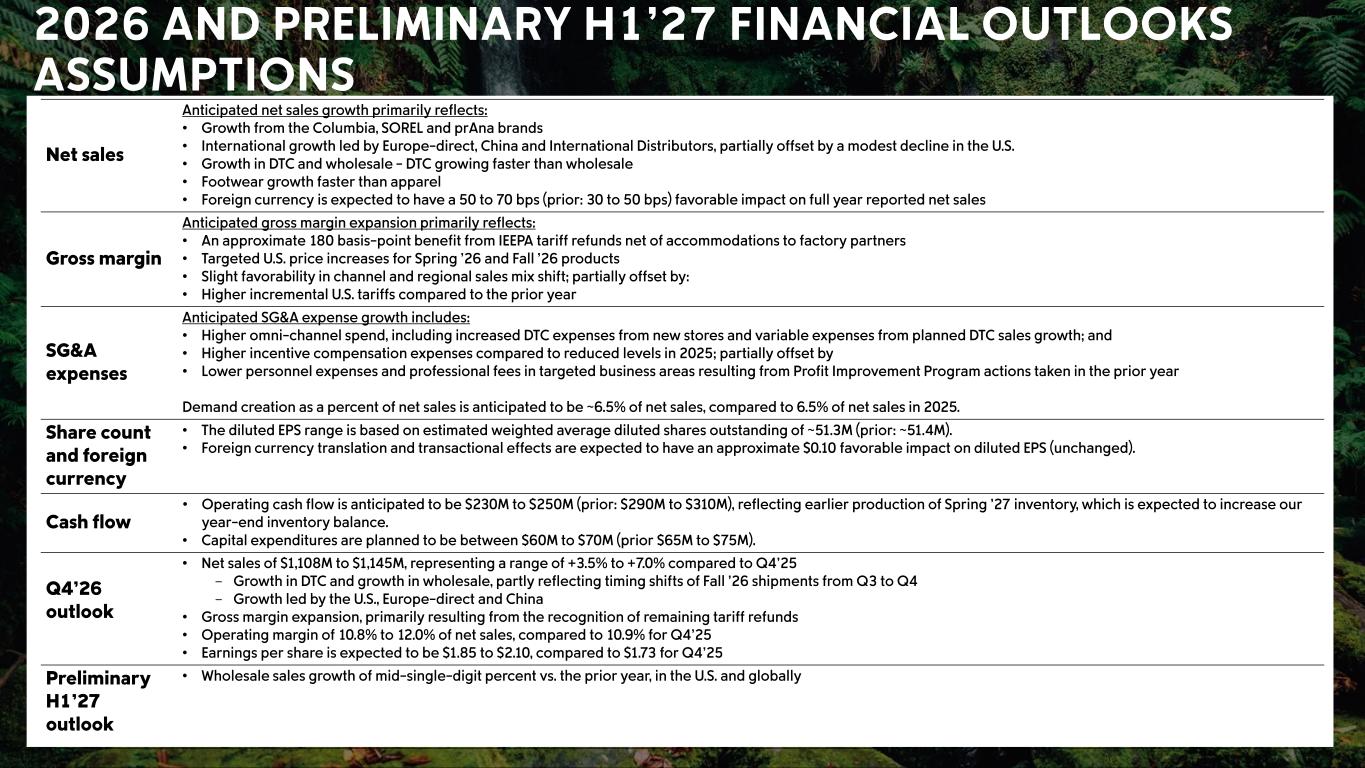
2026 AND PRELIMINARY H1’27 FINANCIAL OUTLOOKS ASSUMPTIONS Net sales Anticipated net sales growth primarily reflects: • Growth from the Columbia, SOREL and prAna brands • International growth led by Europe-direct, China and International Distributors, partially offset by a modest decline in the U.S. • Growth in DTC and wholesale - DTC growing faster than wholesale • Footwear growth faster than apparel • Foreign currency is expected to have a 50 to 70 bps (prior: 30 to 50 bps) favorable impact on full year reported net sales Gross margin Anticipated gross margin expansion primarily reflects: • An approximate 180 basis-point benefit from IEEPA tariff refunds net of accommodations to factory partners • Targeted U.S. price increases for Spring ’26 and Fall ’26 products • Slight favorability in channel and regional sales mix shift; partially offset by: • Higher incremental U.S. tariffs compared to the prior year SG&A expenses Anticipated SG&A expense growth includes: • Higher omni-channel spend, including increased DTC expenses from new stores and variable expenses from planned DTC sales growth; and • Higher incentive compensation expenses compared to reduced levels in 2025; partially offset by • Lower personnel expenses and professional fees in targeted business areas resulting from Profit Improvement Program actions taken in the prior year Demand creation as a percent of net sales is anticipated to be ~6.5% of net sales, compared to 6.5% of net sales in 2025. Share count and foreign currency • The diluted EPS range is based on estimated weighted average diluted shares outstanding of ~51.3M (prior: ~51.4M). • Foreign currency translation and transactional effects are expected to have an approximate $0.10 favorable impact on diluted EPS (unchanged). Cash flow • Operating cash flow is anticipated to be $230M to $250M (prior: $290M to $310M), reflecting earlier production of Spring ’27 inventory, which is expected to increase our year-end inventory balance. • Capital expenditures are planned to be between $60M to $70M (prior $65M to $75M). Q4’26 outlook • Net sales of $1,108M to $1,145M, representing a range of +3.5% to +7.0% compared to Q4’25 - Growth in DTC and growth in wholesale, partly reflecting timing shifts of Fall ’26 shipments from Q3 to Q4 - Growth led by the U.S., Europe-direct and China • Gross margin expansion, primarily resulting from the recognition of remaining tariff refunds • Operating margin of 10.8% to 12.0% of net sales, compared to 10.9% for Q4’25 • Earnings per share is expected to be $1.85 to $2.10, compared to $1.73 for Q4’25 Preliminary H1’27 outlook • Wholesale sales growth of mid-single-digit percent vs. the prior year, in the U.S. and globally
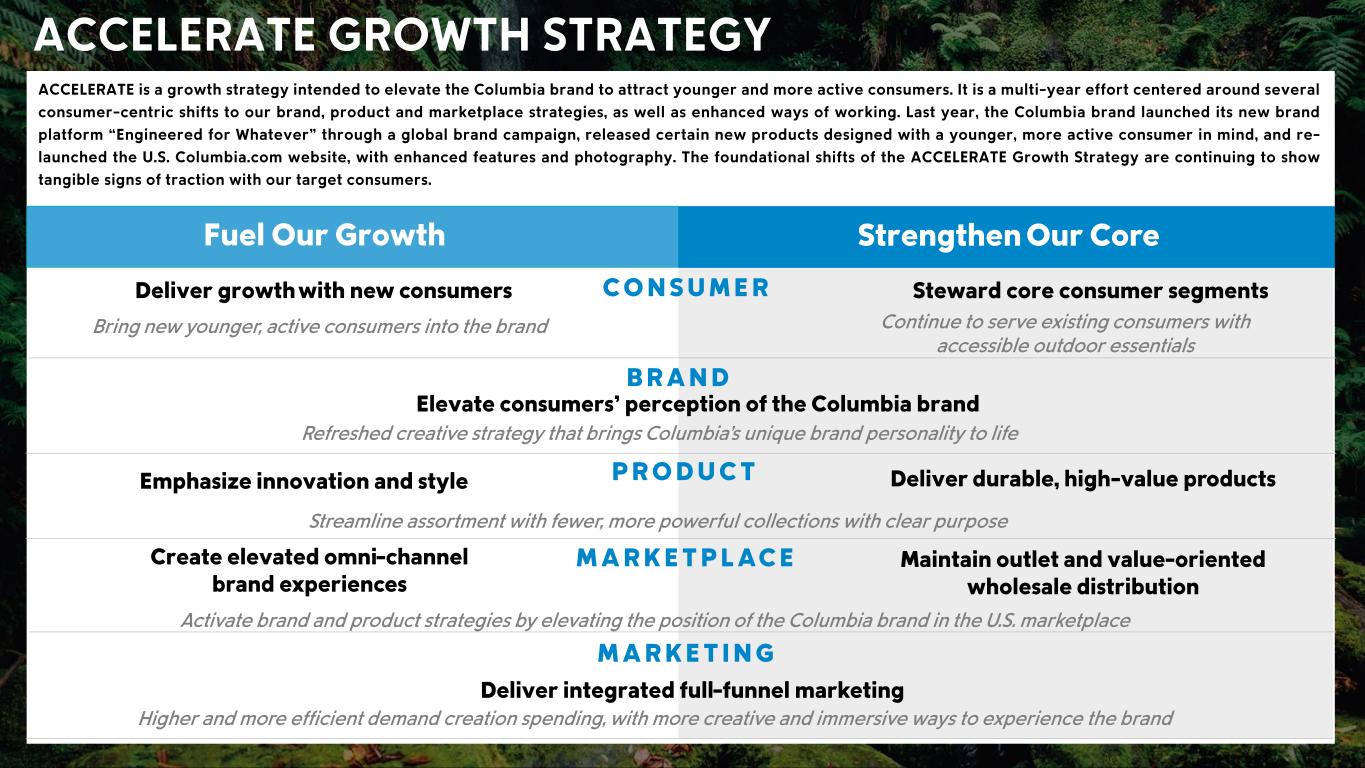
ACCELERATE GROWTH STRATEGY M A R K E T P L AC ECreate elevated omni-channel brand experiences Maintain outlet and value-oriented wholesale distribution Activate brand and product strategies by elevating the position of the Columbia brand in the U.S. marketplace P R O D U C TEmphasize innovation and style Deliver durable, high-value products Streamline assortment with fewer, more powerful collections with clear purpose B R A N D C O N S U M E R Fuel Our Growth Strengthen Our Core Elevate consumers’ perception of the Columbia brand Refreshed creative strategy that brings Columbia’s unique brand personality to life Deliver growth with new consumers Bring new younger, active consumers into the brand Steward core consumer segments Continue to serve existing consumers with accessible outdoor essentials M A R K E T I N G Deliver integrated full-funnel marketing Higher and more efficient demand creation spending, with more creative and immersive ways to experience the brand ACCELERATE is a growth strategy intended to elevate the Columbia brand to attract younger and more active consumers. It is a multi-year effort centered around several consumer-centric shifts to our brand, product and marketplace strategies, as well as enhanced ways of working. Last year, the Columbia brand launched its new brand platform “Engineered for Whatever” through a global brand campaign, released certain new products designed with a younger, more active consumer in mind, and re- launched the U.S. Columbia.com website, with enhanced features and photography. The foundational shifts of the ACCELERATE Growth Strategy are continuing to show tangible signs of traction with our target consumers.
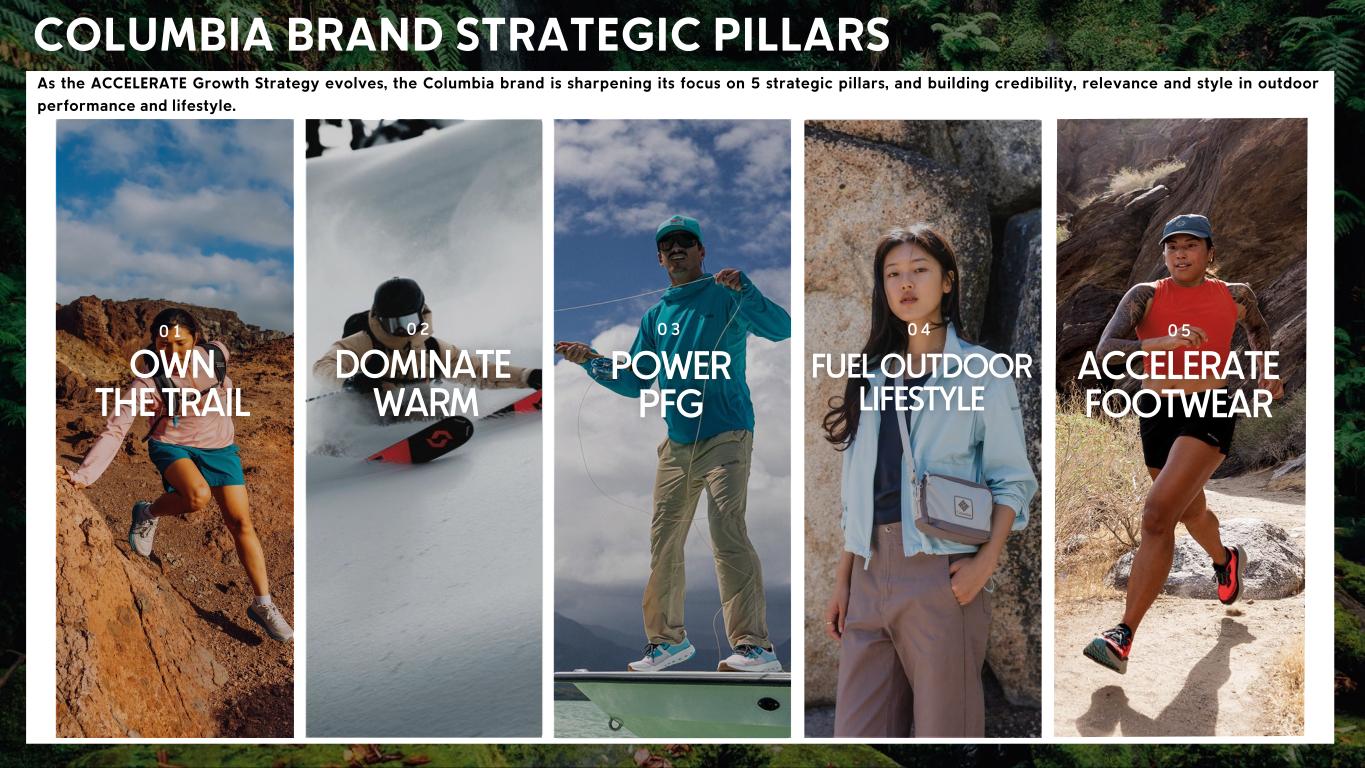
COLUMBIA BRAND STRATEGIC PILLARS 0 50 40 3 OWN THE TRAIL 0 1 DOMINATE WARM 0 2 POWER PFG 0 3 0 4 FUEL OUTDOOR LIFESTYLE ACCELERATE FOOTWEAR 0 5 As the ACCELERATE Growth Strategy evolves, the Columbia brand is sharpening its focus on 5 strategic pillars, and building credibility, relevance and style in outdoor performance and lifestyle.
A P P E N D I X
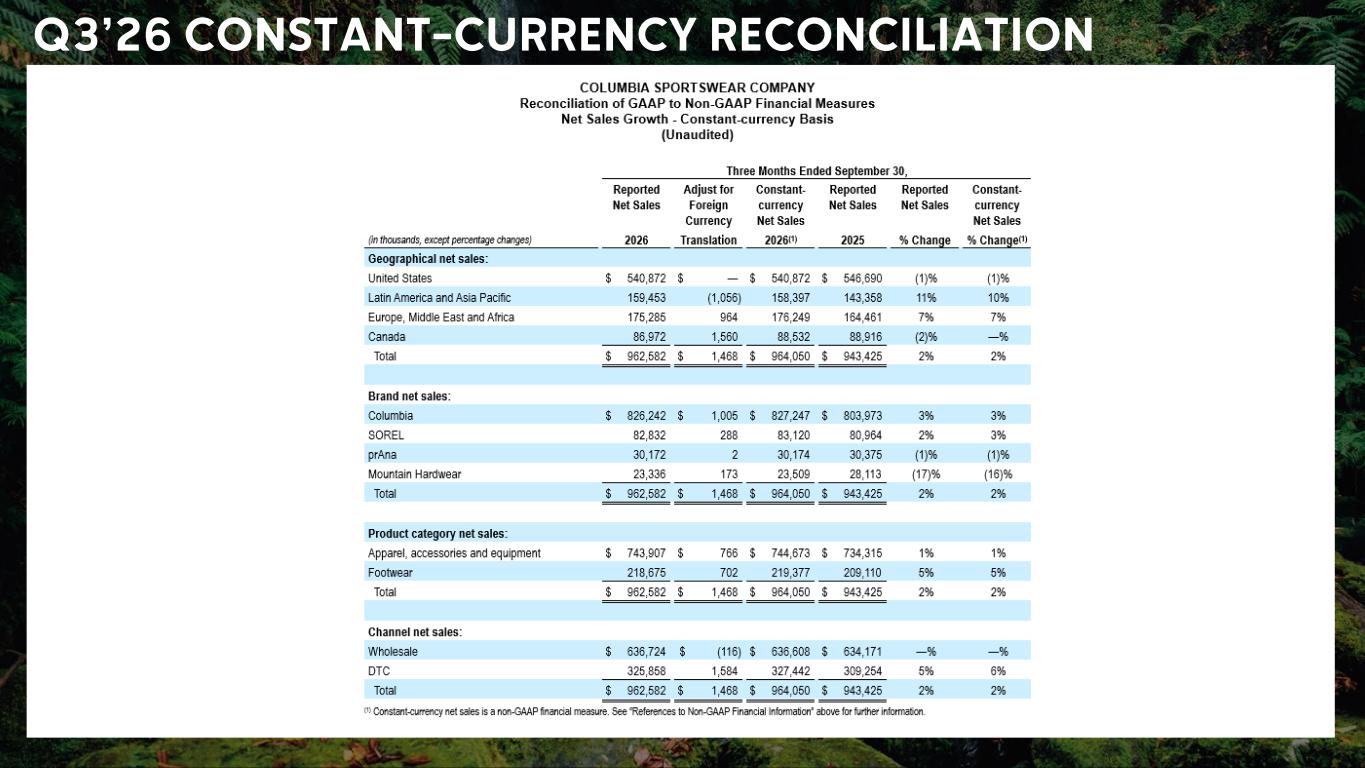
Q3’26 CONSTANT-CURRENCY RECONCILIATION
NINE MONTHS FREE CASH FLOW RECONCILIATION